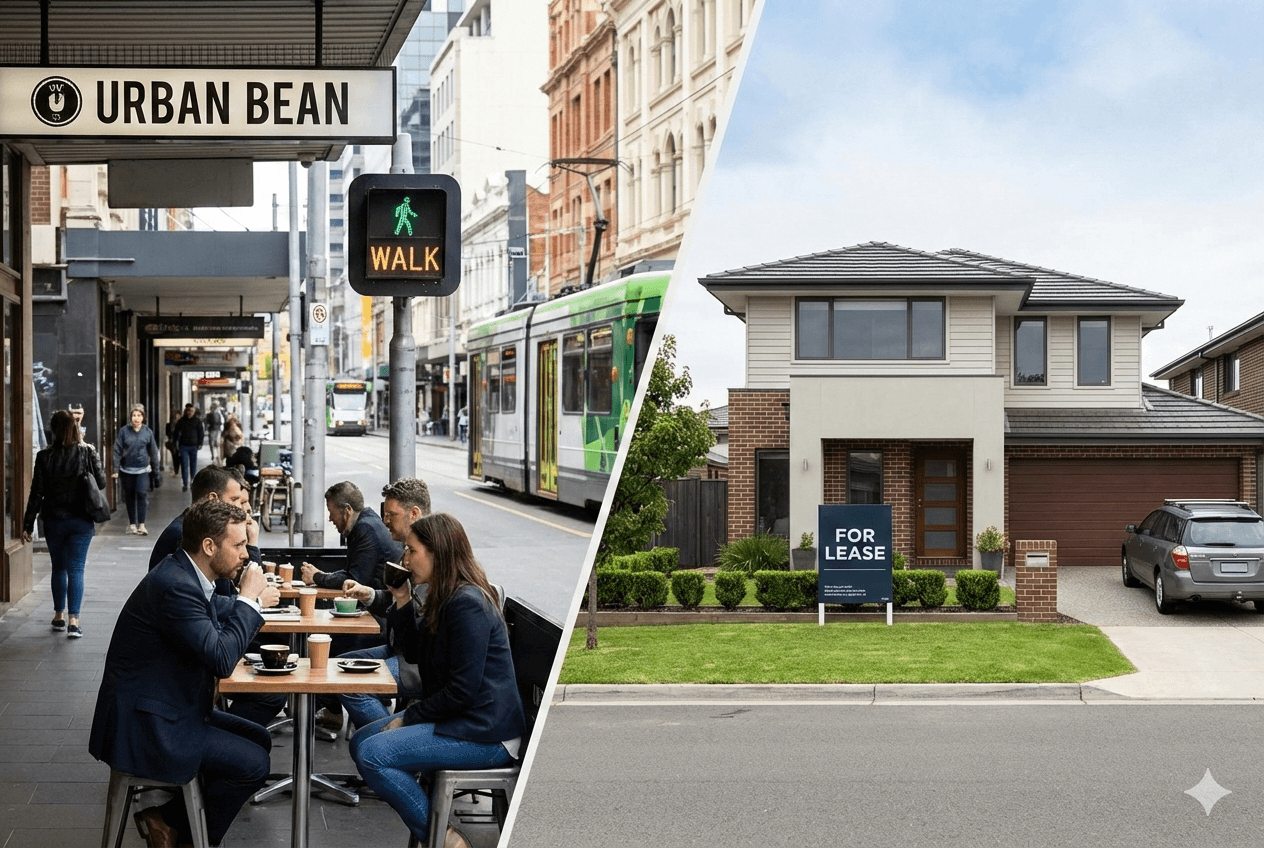
Rentvesting lets you rent where you want to live and buy an investment property where the numbers work. But is it the right strategy for you? We break down how it works, the real financial trade-offs, and who it suits best.
Most Australians face a brutal trade-off: buy somewhere affordable but far from everything that matters, or keep renting and feel like you’re going nowhere. For years that’s been treated as a binary choice — own a home or don’t.
Rentvesting challenges that framing entirely.
The idea is simple. You rent the home you live in — somewhere that suits your job, your social life, your daily rhythm. And you buy an investment property in a more affordable area where the financial fundamentals are strong. Your tenant’s rent helps service the mortgage. You build equity in a property you own, while continuing to live exactly where you want.
This article is for people genuinely weighing up whether rentvesting makes sense for their situation. We’ll walk through how it works, the real numbers, the costs that don’t appear on spreadsheets, and some honest profiles of who it suits and who it doesn’t.
How rentvesting actually works
The mechanics are straightforward. You purchase an investment property in an area chosen purely for its financial merits — strong rental yield, solid growth fundamentals, or both. A tenant moves in and pays rent. That rental income goes toward servicing your investment loan. Meanwhile, you rent your own place in the suburb where you actually want to live.
The key insight is that your investment location is chosen with financial logic, not lifestyle preference. You’re not buying somewhere you’d want to spend your weekends. You’re buying somewhere that builds wealth efficiently while someone else helps pay for it.
Example — Sarah’s situation
Sarah is 29 and works in marketing in Surry Hills, Sydney. Buying a mid-range one bedroom apartment nearby would cost $850,000. Instead, she rents a one-bedroom in Newtown for $650 a week and owns a $520,000 unit in Woolloongabba, Brisbane. Her tenant pays $480 a week, covering most of her investment loan repayments. She lives where her career and social life demand. Brisbane does the financial heavy lifting. In three to five years, she plans to use the equity she’s built — plus any capital growth — as a springboard toward buying in Sydney, or to add a second investment property.
Who does this suit? Generally, it appeals to first-home buyers priced out of the suburbs they actually want to live in, young professionals who may relocate within five years, and anyone willing to separate the question of “where do I live best” from “where does my money work hardest.”
Why so many Australians are doing this now
The short answer: the gap between where people want to live and where they can afford to buy has never been wider.
Sydney’s median house price sits above $1.6 million as of early 2026 (PropTrack / Cotality data). At that price, a 20% deposit means saving roughly $320,000 before you’ve paid a single cent in repayments, insurance, or stamp duty. Even with a 10% deposit and the expanded First Home Guarantee scheme, the servicing cost on a Sydney mortgage is punishing for most single incomes.
The data reflects the shift. The Australian Bureau of Statistics recorded over 8,200 new home loan commitments by first-home buyers for investment purposes in 2024 — a 12% jump on the prior year. Owner-occupier loans from the same cohort grew only 5%. In NSW specifically, first-home buyers taking out investment loans surged 16% in the September 2025 quarter alone. Rentvesting isn’t a fringe idea anymore — it’s becoming a mainstream entry strategy.
The geographic pattern is consistent: renters in Sydney and Melbourne are buying investment properties in Queensland, South Australia, and Western Australia, where entry prices are lower, rental yields are stronger, and population growth is fuelling demand. Perth, Adelaide, and Brisbane all outperformed Sydney and Melbourne on price growth through 2025, and most forecasters expect that to continue through 2026.
The financial logic in plain English
The core arithmetic of rentvesting rests on one observation: renting a home in a premium suburb is frequently far cheaper than servicing a mortgage on the same property. The gap isn’t small — it can run 30% to 50% depending on the suburb and current interest rates.
Lane Cove, Sydney — a quick comparison:
– Owning: The median house price in Lane Cove, Sydney is $2.8M. With a 20% deposit, your looking at mortgage repayments of around $13,000/month (principal & interest over 30 years at 5.5%)
– Renting the same suburb: Median rental for a comparable property sits around $5,250/month or a rental yield of 2.2%.
Thats as cash flow difference of $7,750 per month between buying and renting. In a rentvesting setup, you redirect that saving toward servicing an investment loan in a market where the numbers stack up — and your tenant’s rent offsets a significant portion of the cost.
Say you invest in a duplex in Buderim, Sunshine Coast for $1,050,000. With a 3-bedroom dwelling renting at $670 per week and a 2-bedroom at $515 per week, your two tenants together contribute $1,185 per week or $5,135 per month toward your loan costs. You build equity in a single asset you own, while two income streams cover the bulk of your repayments. Of course, if you can afford to buy a $2.8M home to live in, you can usually afford and even larger investment portfolio. But notice how the $1.05M investment property generates almost the same rental as the $2.8M Sydney home. These are the sorts of options that rentvesting open up.
The stamp duty trap worth understanding
There’s a hidden cost to buying a home you’re not sure about. If you purchase a $900,000 property in NSW and sell within three years, you’ll have paid around $35,000 in stamp duty and $18,000 to $27,000 in agent’s fees — more than $50,000 gone before a single dollar of capital growth is realised. If the market’s been flat, you walk away with less than you started with. Rentvesting sidesteps this by directing your purchase toward a property chosen solely because the numbers work, not because it was the closest compromise to where you wanted to live.
Tax advantages — briefly
Investment properties unlock deductions that owner-occupied homes don’t: negative gearing (deducting investment losses against your income), depreciation on the building and fixtures, and a 50% capital gains tax discount if you hold for more than 12 months. These can meaningfully improve your after-tax position. We’ll cover the tax mechanics in a separate strategic guide.
What rentvesting costs you — be honest
Rentvesting has real trade-offs, here’s what you need to weigh.
You forfeit first-home buyer concessions
In most states, once you purchase an investment property you permanently lose eligibility for first home owner grants and stamp duty concessions. Depending on your state and purchase price, that’s $10,000 to $50,000+ off the table.
The federal Help to Buy scheme — which offers a government equity co-purchase of 30–40% — is also incompatible with rentvesting. If you qualify and the shared-equity model suits your situation, it may be more valuable than investing first.
You remain a tenant
This is the cost that doesn’t show up in a spreadsheet. As a renter, you’re subject to rent increases, lease non-renewals, and the low-level uncertainty that comes with not owning the roof over your head. What can you do? Negotiate at least a 24 month lease where possible. Budget so that rent stays comfortably below 30% of your gross income. Build a relocation cash buffer — enough to cover bond, moving costs, and a few weeks of overlap if you need to move at short notice.
Investment property costs are real
Your investment won’t always have a tenant. Budget for vacancy periods. You’ll also carry property management fees (typically 7–10% of rental income), landlord insurance, maintenance, council rates, and strata if applicable. Run your numbers with a realistic cost model, not a best-case scenario.
Is rentvesting right for you? A practical gut-check
Rentvesting is a strategy, not a universal answer. The right call depends entirely on your numbers, your timeline, and your tolerance for the particular uncertainties that come with being both a landlord and a tenant simultaneously.
Strong candidate: A 27-year-old professional renting in Surry Hills. $120k income, no dependants, and at least a five-year horizon before needing a family home. Buying in the inner city would require a $250k+ deposit and significant repayments. Rentvesting lets them enter the market now, build equity, and reassess in five years with a much stronger balance sheet.
Worth considering carefully: A 38-year-old with two school-age kids, renting in Dee Why. The family needs stability — school zones matter, landlord decisions to sell can be disruptive, and the emotional weight of not owning your family home is real. Rentvesting could still work here, but the stability risks are meaningful and need to be weighed against the financial upside.
Probably not the right fit: A 31-year-old in regional Queensland who could buy a solid owner-occupied home for $420,000. With access to the full First Home Owner Grant, stamp duty concessions, and a lower owner-occupier interest rate, buying your own place likely outweighs the rentvesting benefits. The numbers just don’t demand the workaround.
Questions to ask yourself: Can I cover rent, investment loan repayments, and a three-month vacancy buffer at the same time — comfortably? Am I settled enough in my current location to sustain renting for three to seven years? Do I have a clear timeline and plan for eventually buying my own home, or am I drifting?
That last point matters more than anything else in this article. The best way to know whether rentvesting is right for you is to model both paths side by side, with real rates, real costs, and real assumptions about your income and lifestyle. A good mortgage broker will do that with you in an hour. Your gut can’t.
Want to model both paths?
If you’re weighing up rentvesting against the traditional route, we can run both scenarios for your specific situation — income, savings, location, timeline. No obligation, just clarity.
Book a free strategy session →
Disclaimer: The content of this article is general in nature and is presented for informative purposes. It is not intended to constitute tax or financial advice, whether general or personal nor is it intended to imply any recommendation or opinion about a financial product. It does not take into consideration your personal situation and may not be relevant to circumstances. Before taking any action, consider your own particular circumstances and seek professional advice. This content is protected by copyright laws and various other intellectual property laws. It is not to be modified, reproduced or republished without prior written consent.